Wk47 MacroTechnicals - 75bp hike!
Sticky inflation. Three straight 25bp hikes underpriced. Nvidia the AI trade’s earnings test
Pardon the click-baity headline, but let's just start but saying that I'm not completely sold on a 50bp hike at the December meeting as implied by Waller, let alone a 75bps hike. I do however see back-to-back hikes over the next three meetings amounting to +75bps. We'll take a deeper dive into the inflation data to show why. We'll then take a close look at US equity market internals and the AI trade, particularly as it relates to an Nvidia without Jensen. Retail sees value, but seasoned professionals see a fast-growing tumour spreading throughout the AI ecosystem. Finally, we'll review our macro frameworks and event calendar to shape our tactical biases for the week ahead.
Inflation 'Broadening'
September Core CPI printed an uncomfortable 0.296% and another consecutive rise in the YoY rates. Cleveland Fed sees core cooling off in November, but it is worth remembering that their August forecast of 0.2% for September had widely missed the mark of 0.34% was 0.30% prints respectively.
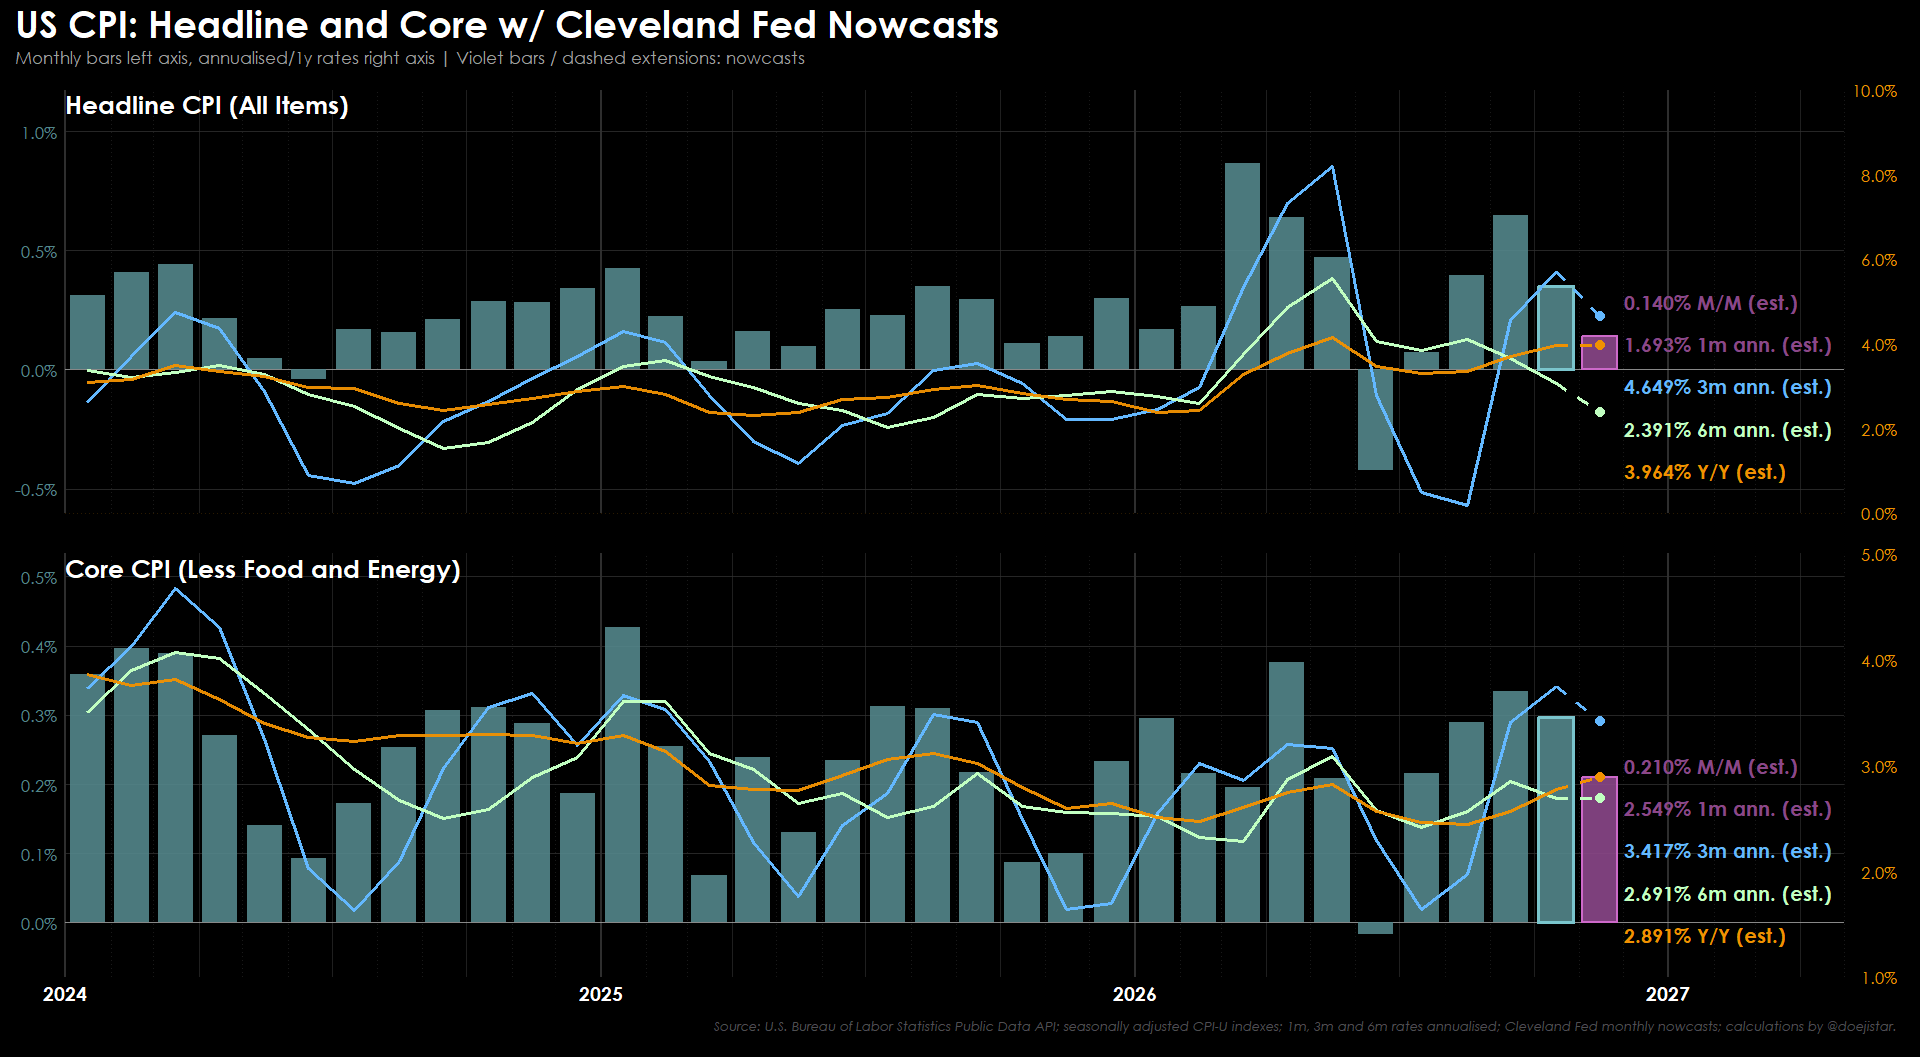
While 'broadening' has become the latest buzzword to be trending among Fed members, we've seen inflation breadth narrow in October and breaking the streak of 8 straight months of the majority of CPI components running above 3% YoY. The distribution still weighs more heavily on the higher side however with the peak shifting rightwards (higher) while median CPI shifted lower.
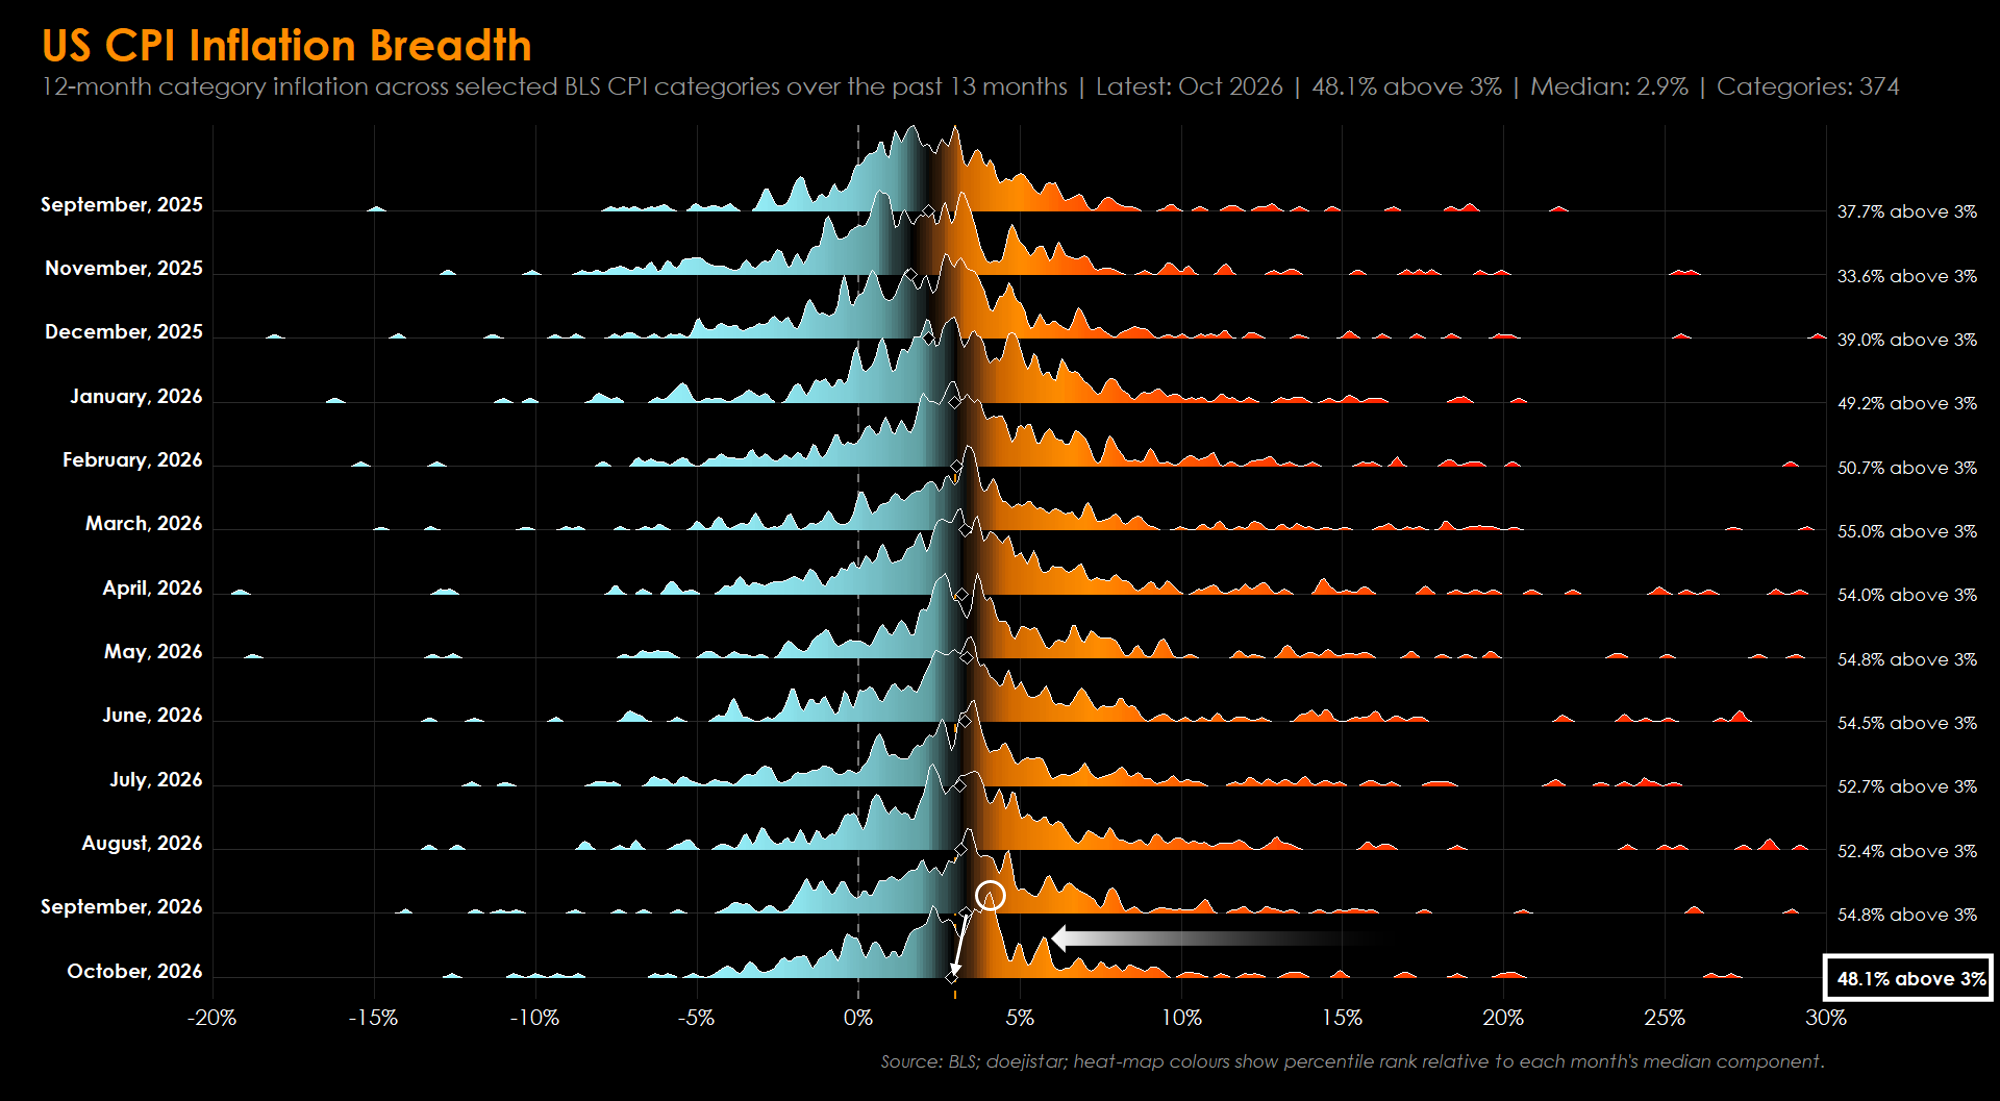
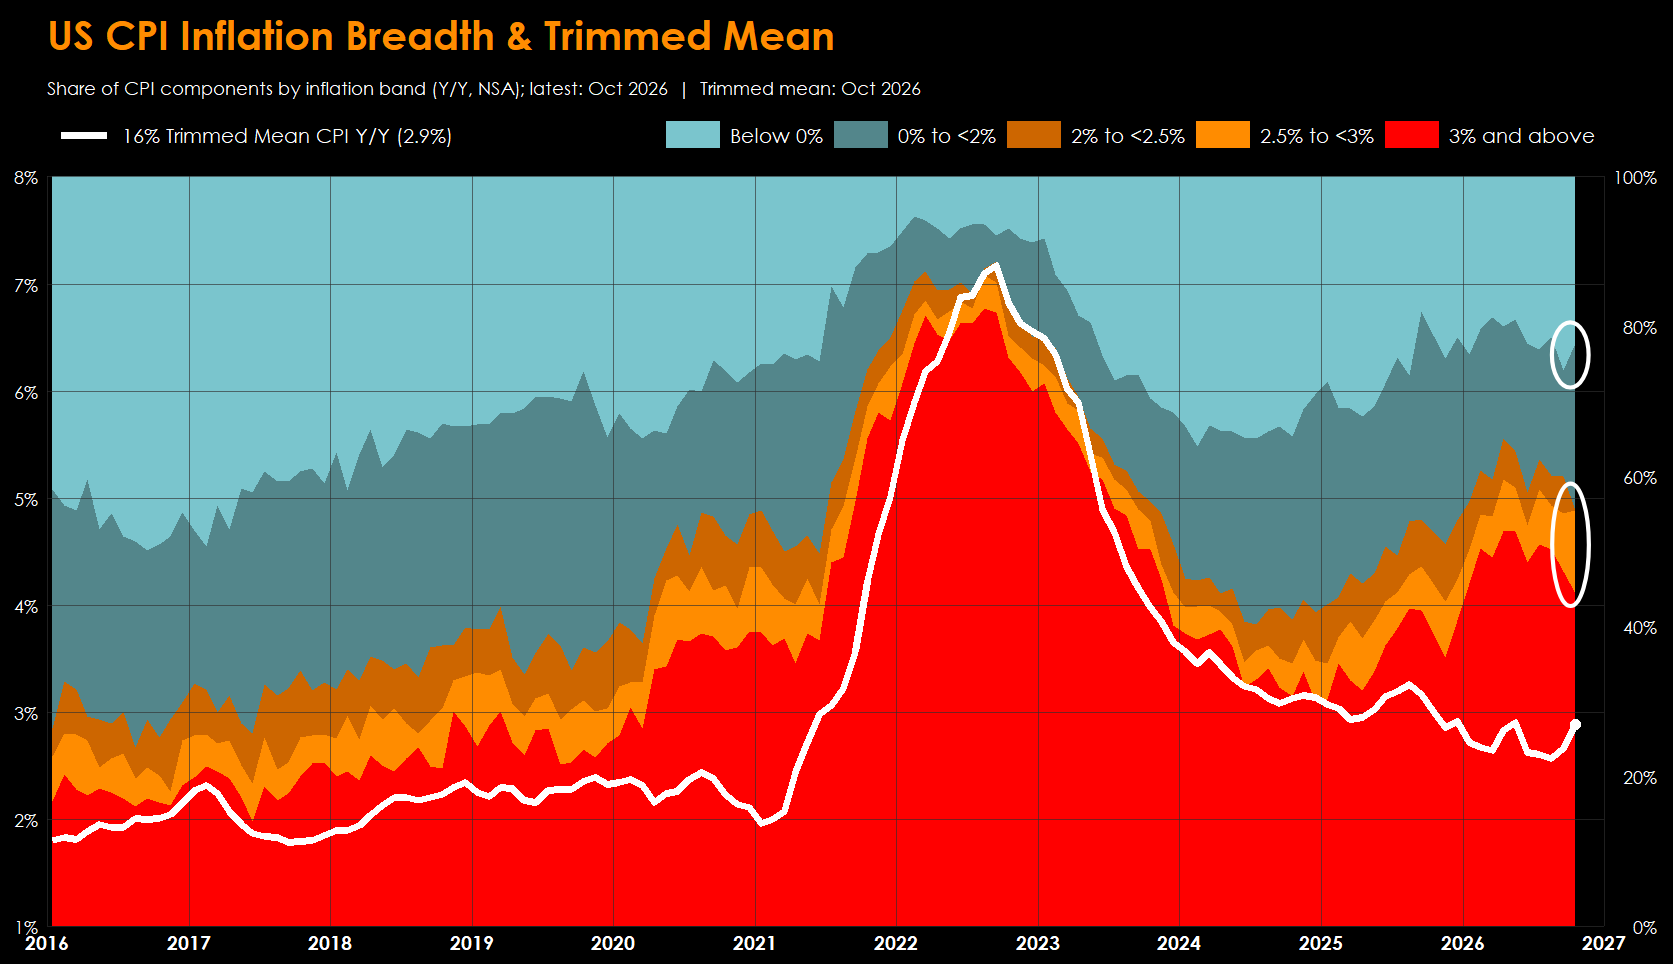
Inflation has eased in some of the categories that previously saw the fastest price rises, but evidence of broadening can still be observed. Fewer components are seeing prices fall year on year, and more are running between 2.5% and 3.0%.
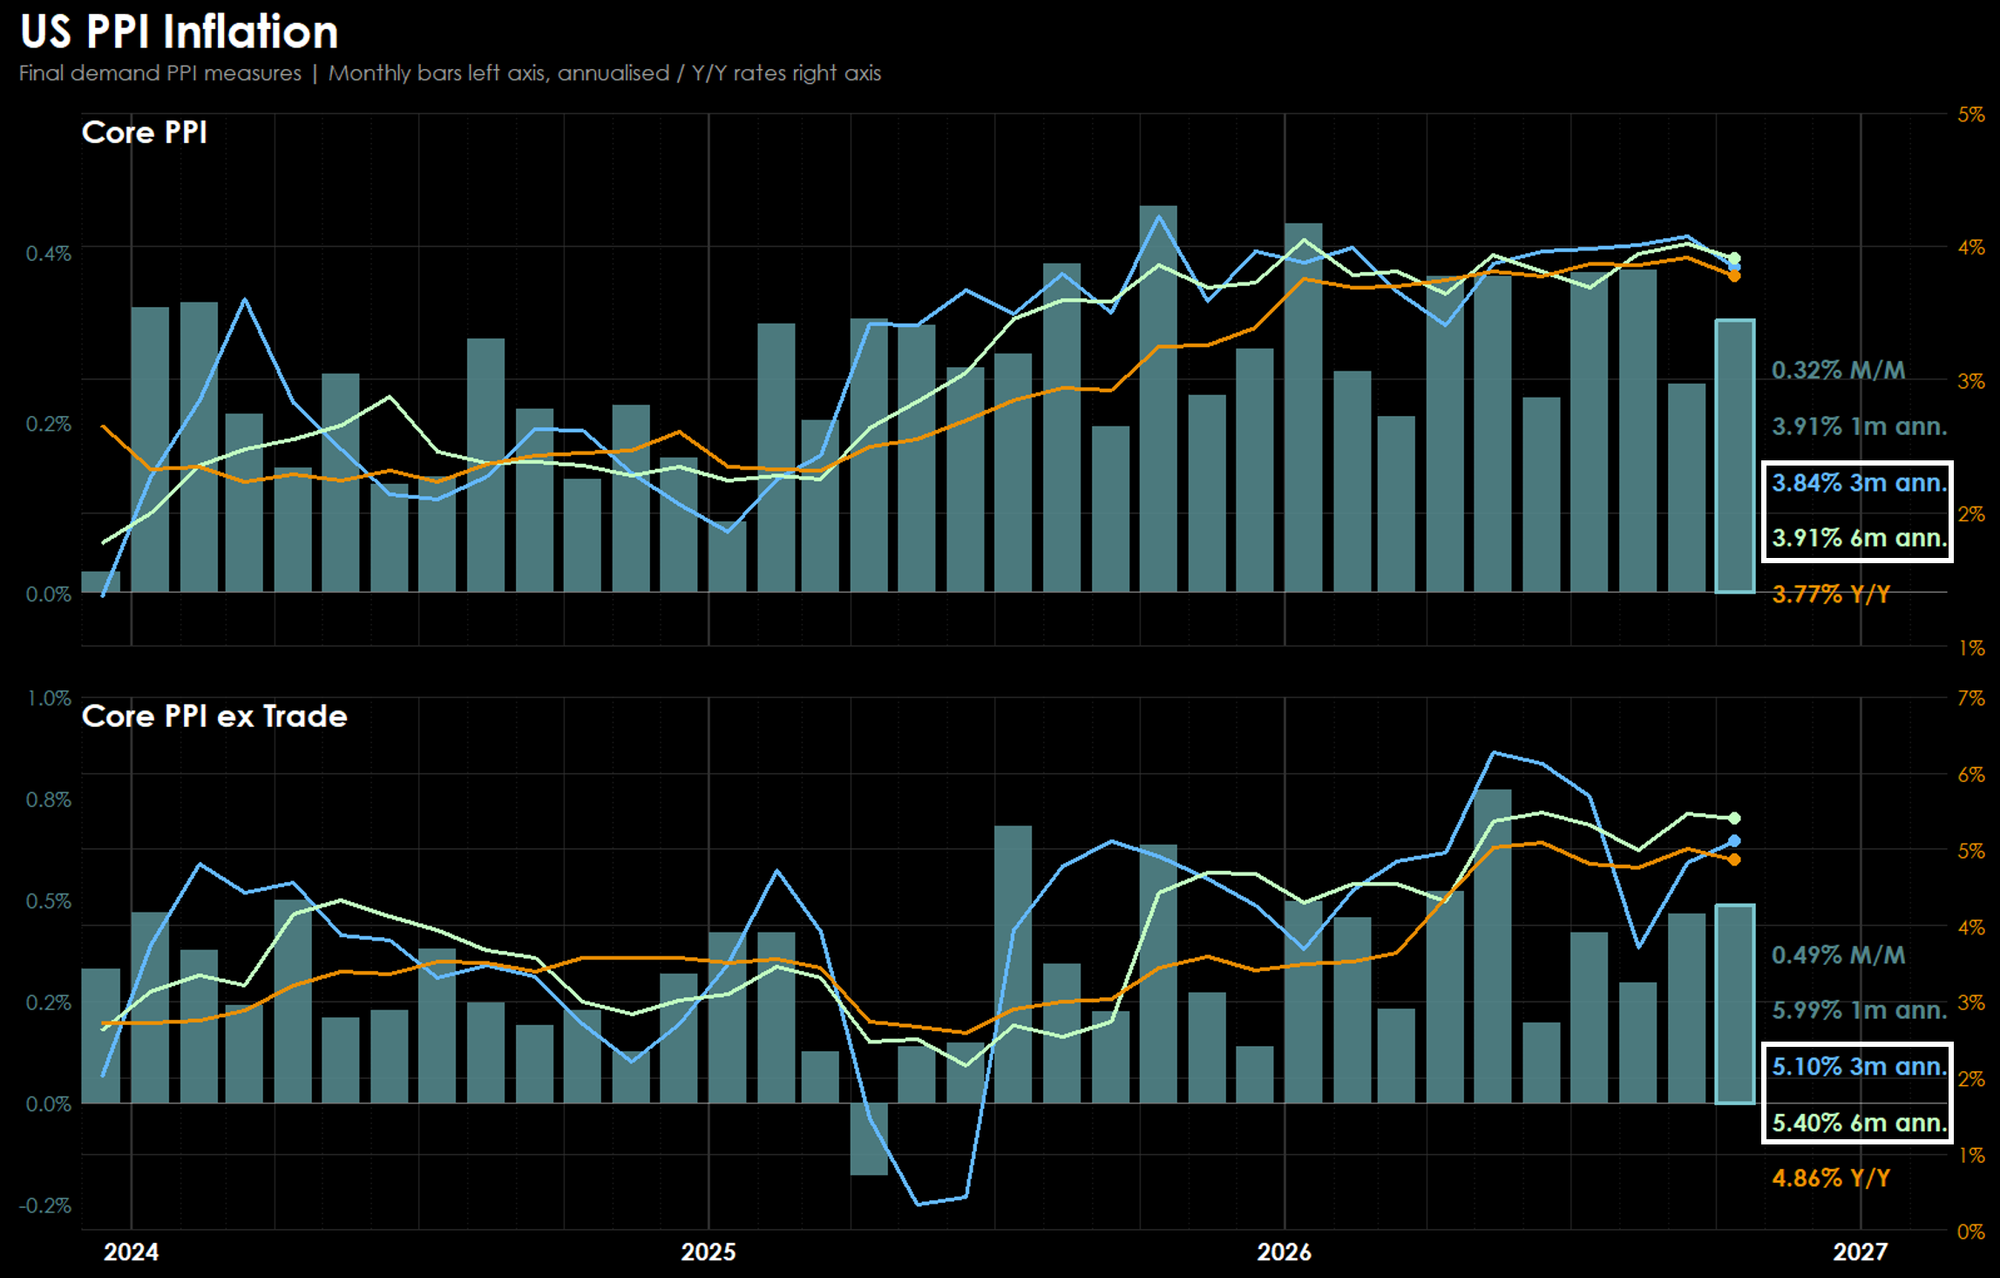
It is often argued CPI lags and therefore PPI to be more informative on inflation trends due to its close proximity to changes in the macro environment (e.g. tariffs and energy prices). Even so, the latest report offers no easing of concerns. Core PPI was in line with expectations but another firm monthly increase puts the 3 and 6-month trend close to 4% annualised. Core ex-trade was 0.49% above the 0.3% expected keeping the 3 and 6-month annualised rates above 5%.
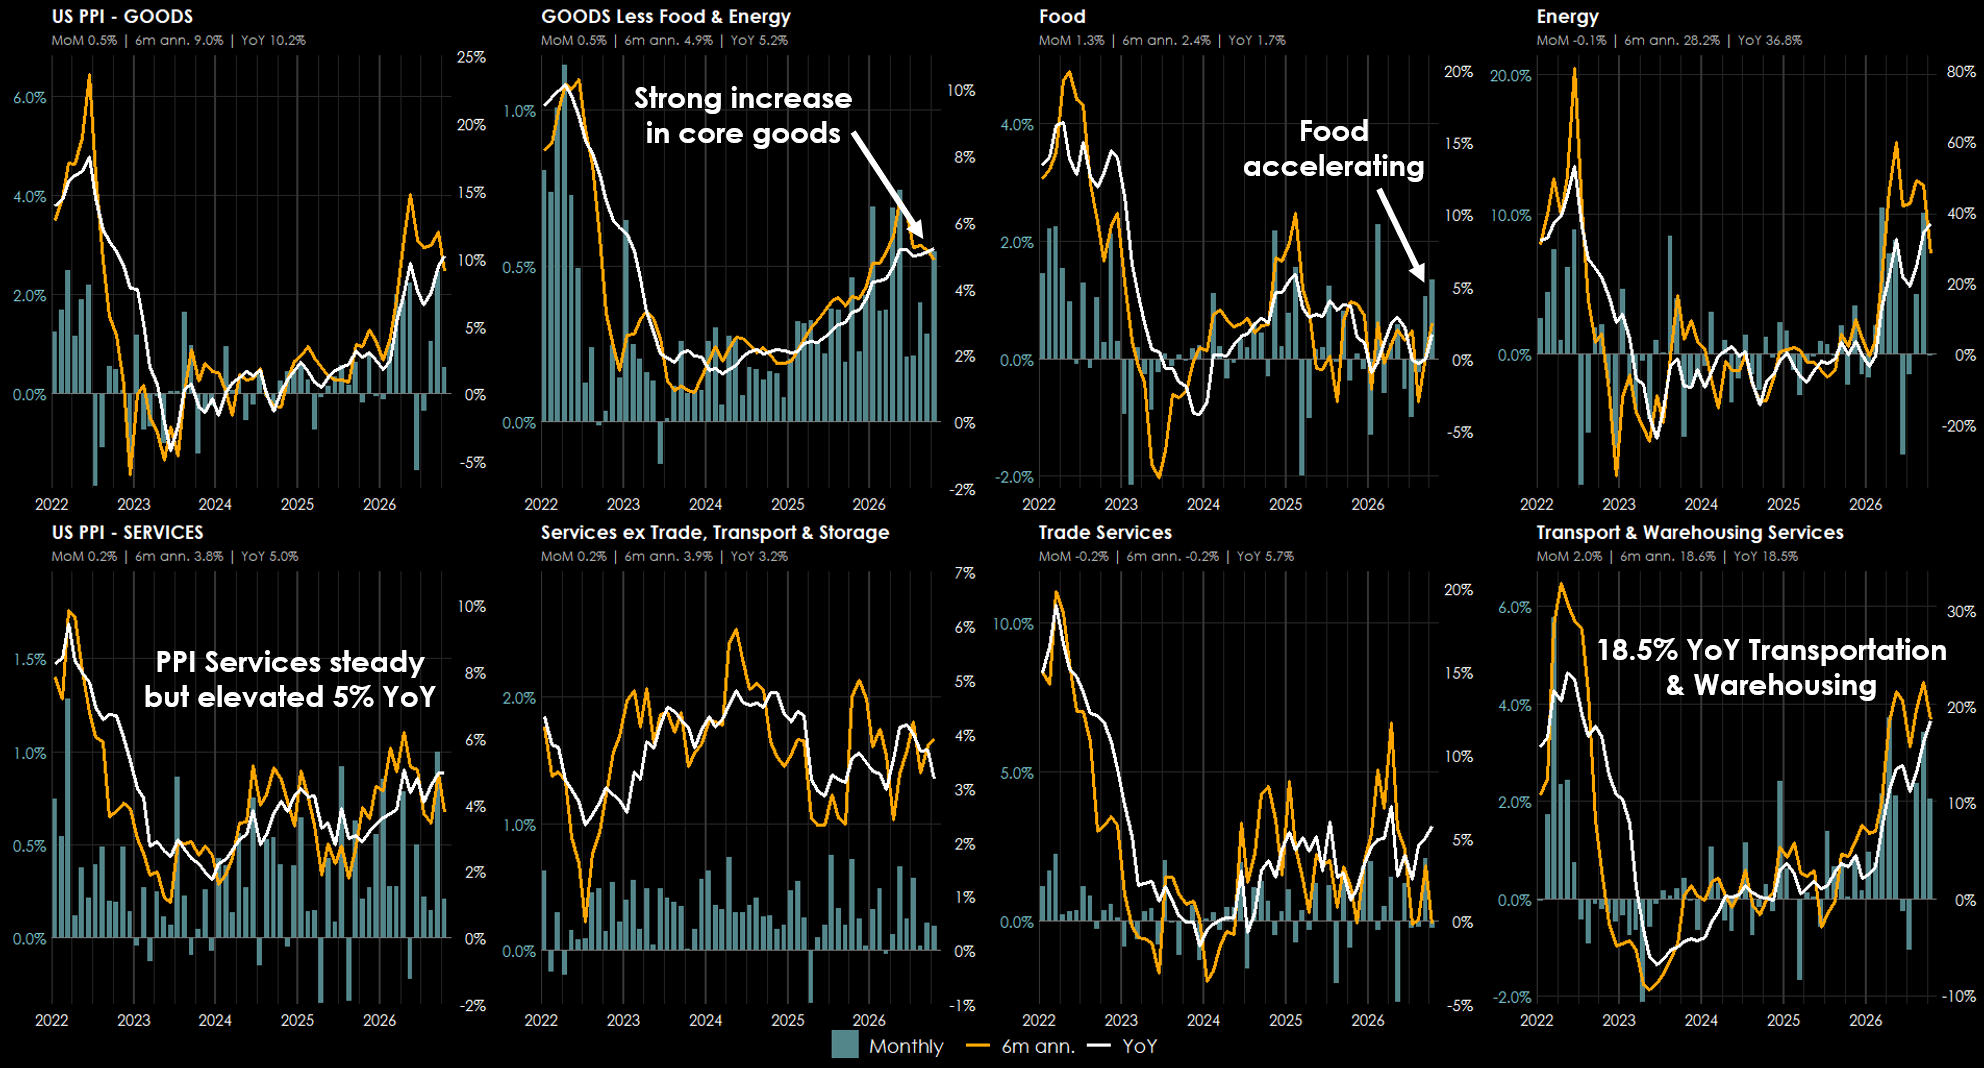
Energy was down -0.1% but core goods and food categories are accelerating while Transport & warehousing is still at extremely high levels.
As flagged in the Wk42 note, inflation has strong seasonal patterns. Non-seasonally adjusted CPI data going back 40 years shows the final months of the year to be the weakest due to seasonal discounts and sales, and strongest at the beginning of the year when discounts and sales normalise.
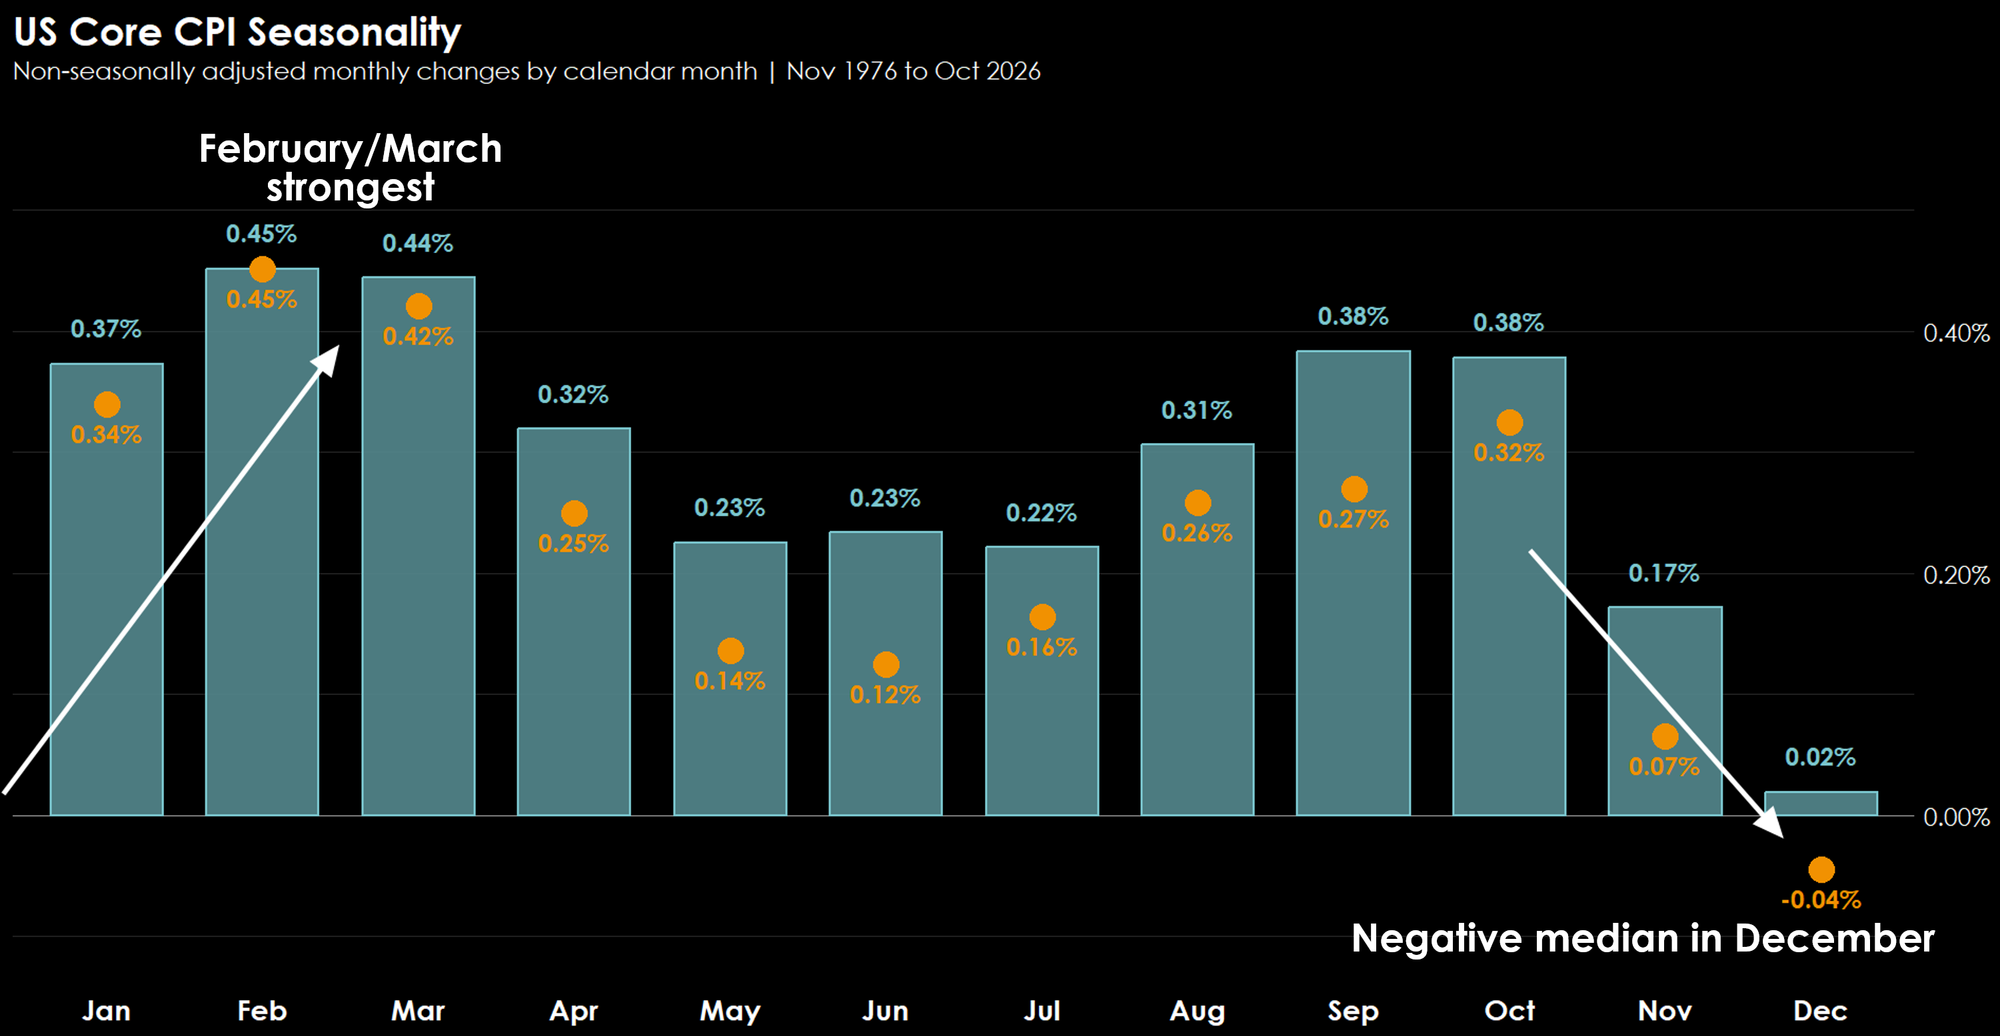
Aside the normalisation from seasonal discounts, strong Q1 inflation can also explained by - 1) stock markets tend to be strong during the Q4 and Q1 periods boosting households sense of wealth, 2) majority of employee bonuses are received at the beginning of the year^, 3) seasonal price-settings/repricings*, and 4) Federal tax refunds/returns being processed in February - all of which amount to tailwinds for stronger consumer spending.
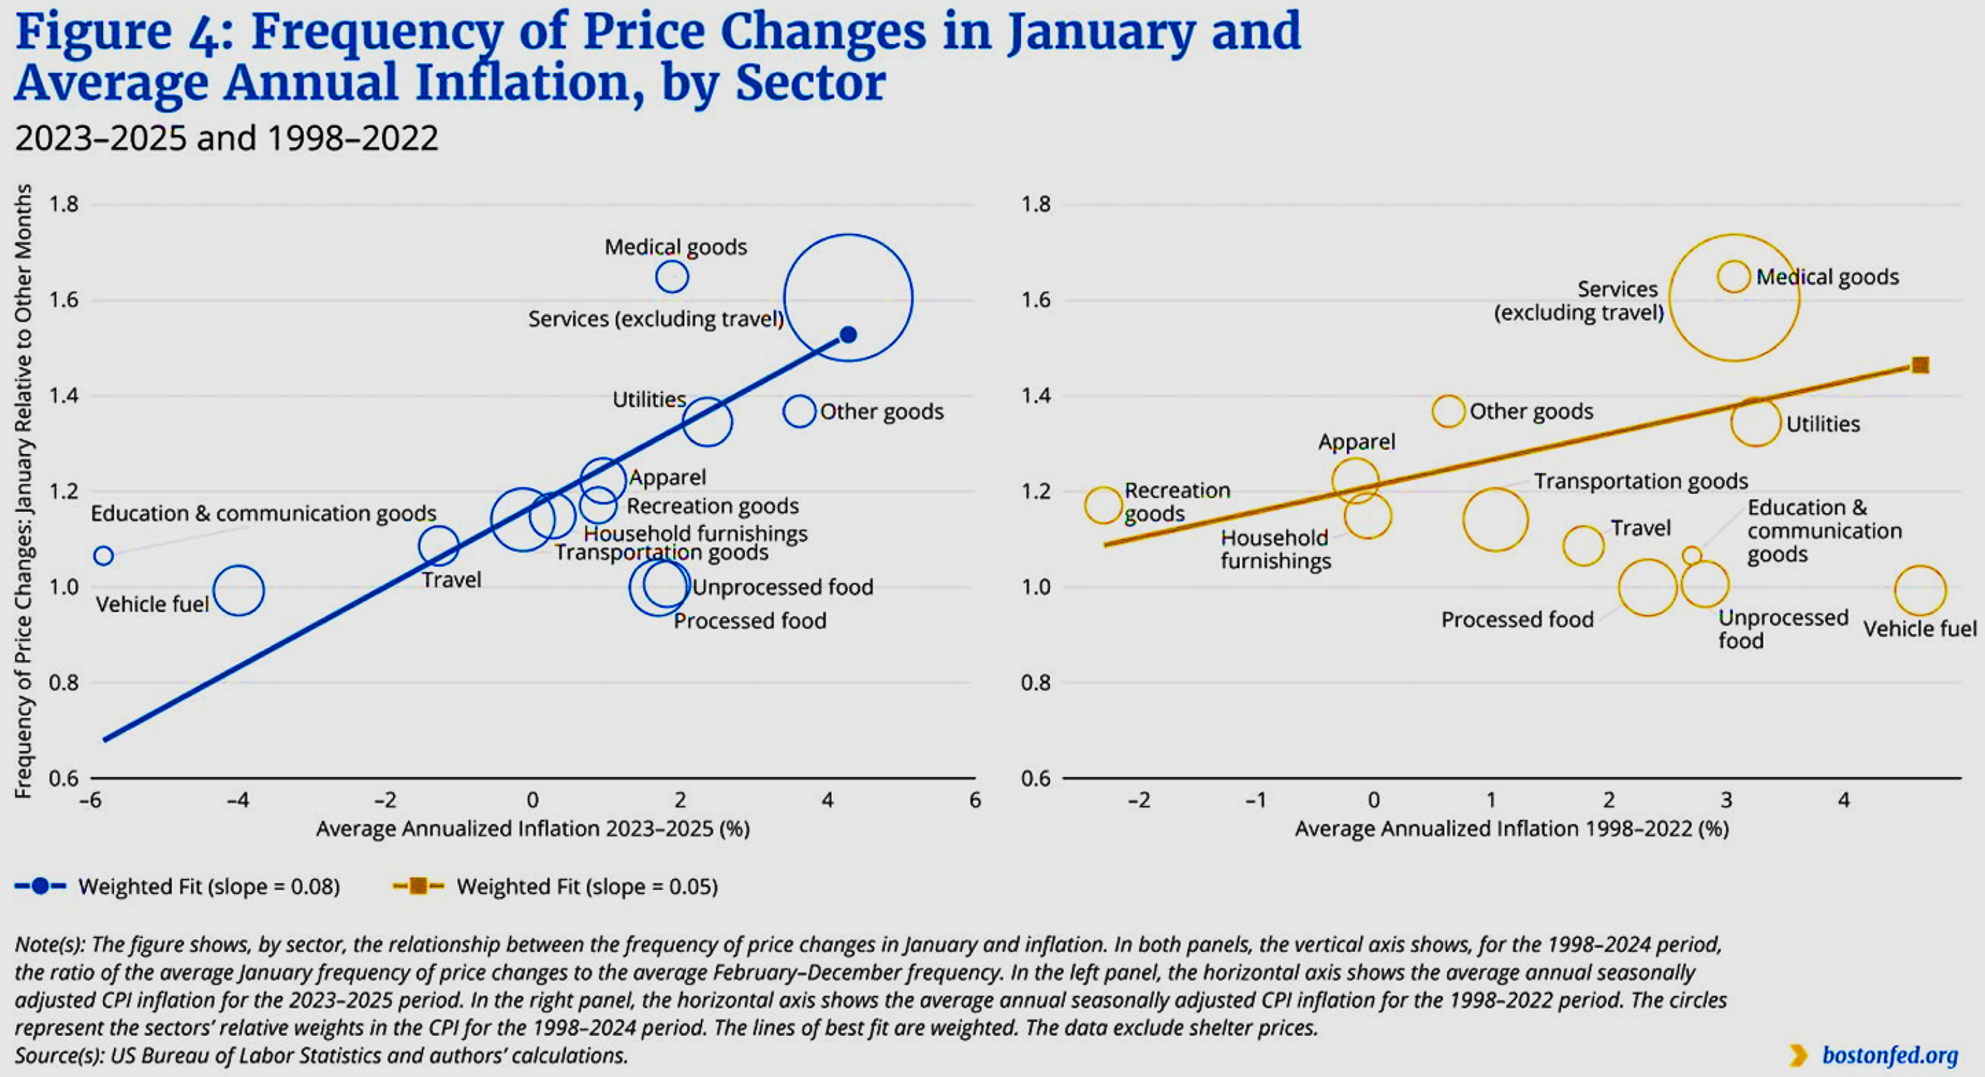
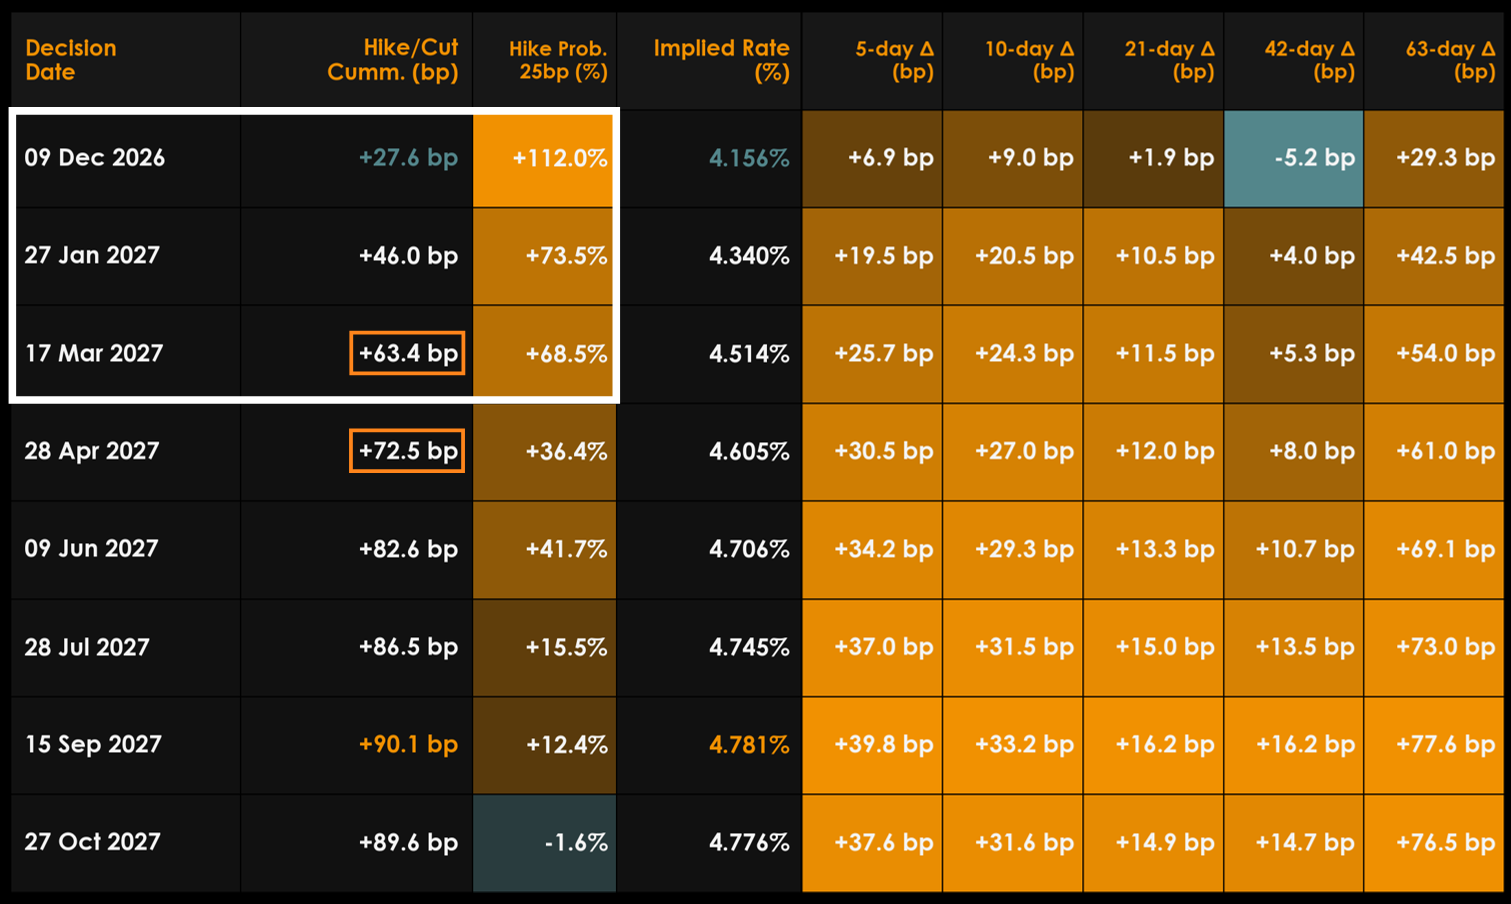
These are critical months for the inflation outlook as we head into a seasonally weak period with both firm and 'broad' inflation pressures such that if broad inflation pressures persist during these months, that would make three back-to-back 25bps hikes a highly probable scenario, a scenario of which the market is underpriced for with +63.4bps priced over the next 3 meetings, and 72.5bps priced over the next 4 meetings.