Wk44 MacroTechnicals - The Inflection Trade
Inflection watch: inverted VIX and shifting correlations
This week I examine the case for a potential inflection in US growth stocks and the dollar via narrative based pivot levels from recent history, VIX inversions, and shifting correlations for confirmation. I also explore the widening WTI–Brent spread and how geopolitical risks complicate the timing of these trade ideas, and thus urging cautiously optimistic but an opportunistic trading stance.
Inflection Watch
On Wednesday I flagged a combination of signals that pointed to a potential inflection point for risk assets along with some macro reasons why I think an inflection is near: 1) financial conditions loosened, and 2) still early in the AI cycle evidenced by a massively wide positive output gap (i.e. an extreme shortage of supply versus ever-increasing demand for compute).
Looking at the Growth/Value ratio, two critical points come to mind with regards to major Growth/Value inflection points in recent history: 1) 2022/23 recession-inducing monpol tightening that led to a massive rise in real rates hit high-beta and unprofitable tech-stocks, and 2) 2024/25, a transformative period when the AI cycle in stocks essentially began. I would consider the pivot areas across both of those periods to serve as the base for the next inflection-point should the early-in-the-AI-cycle assumption hold true.
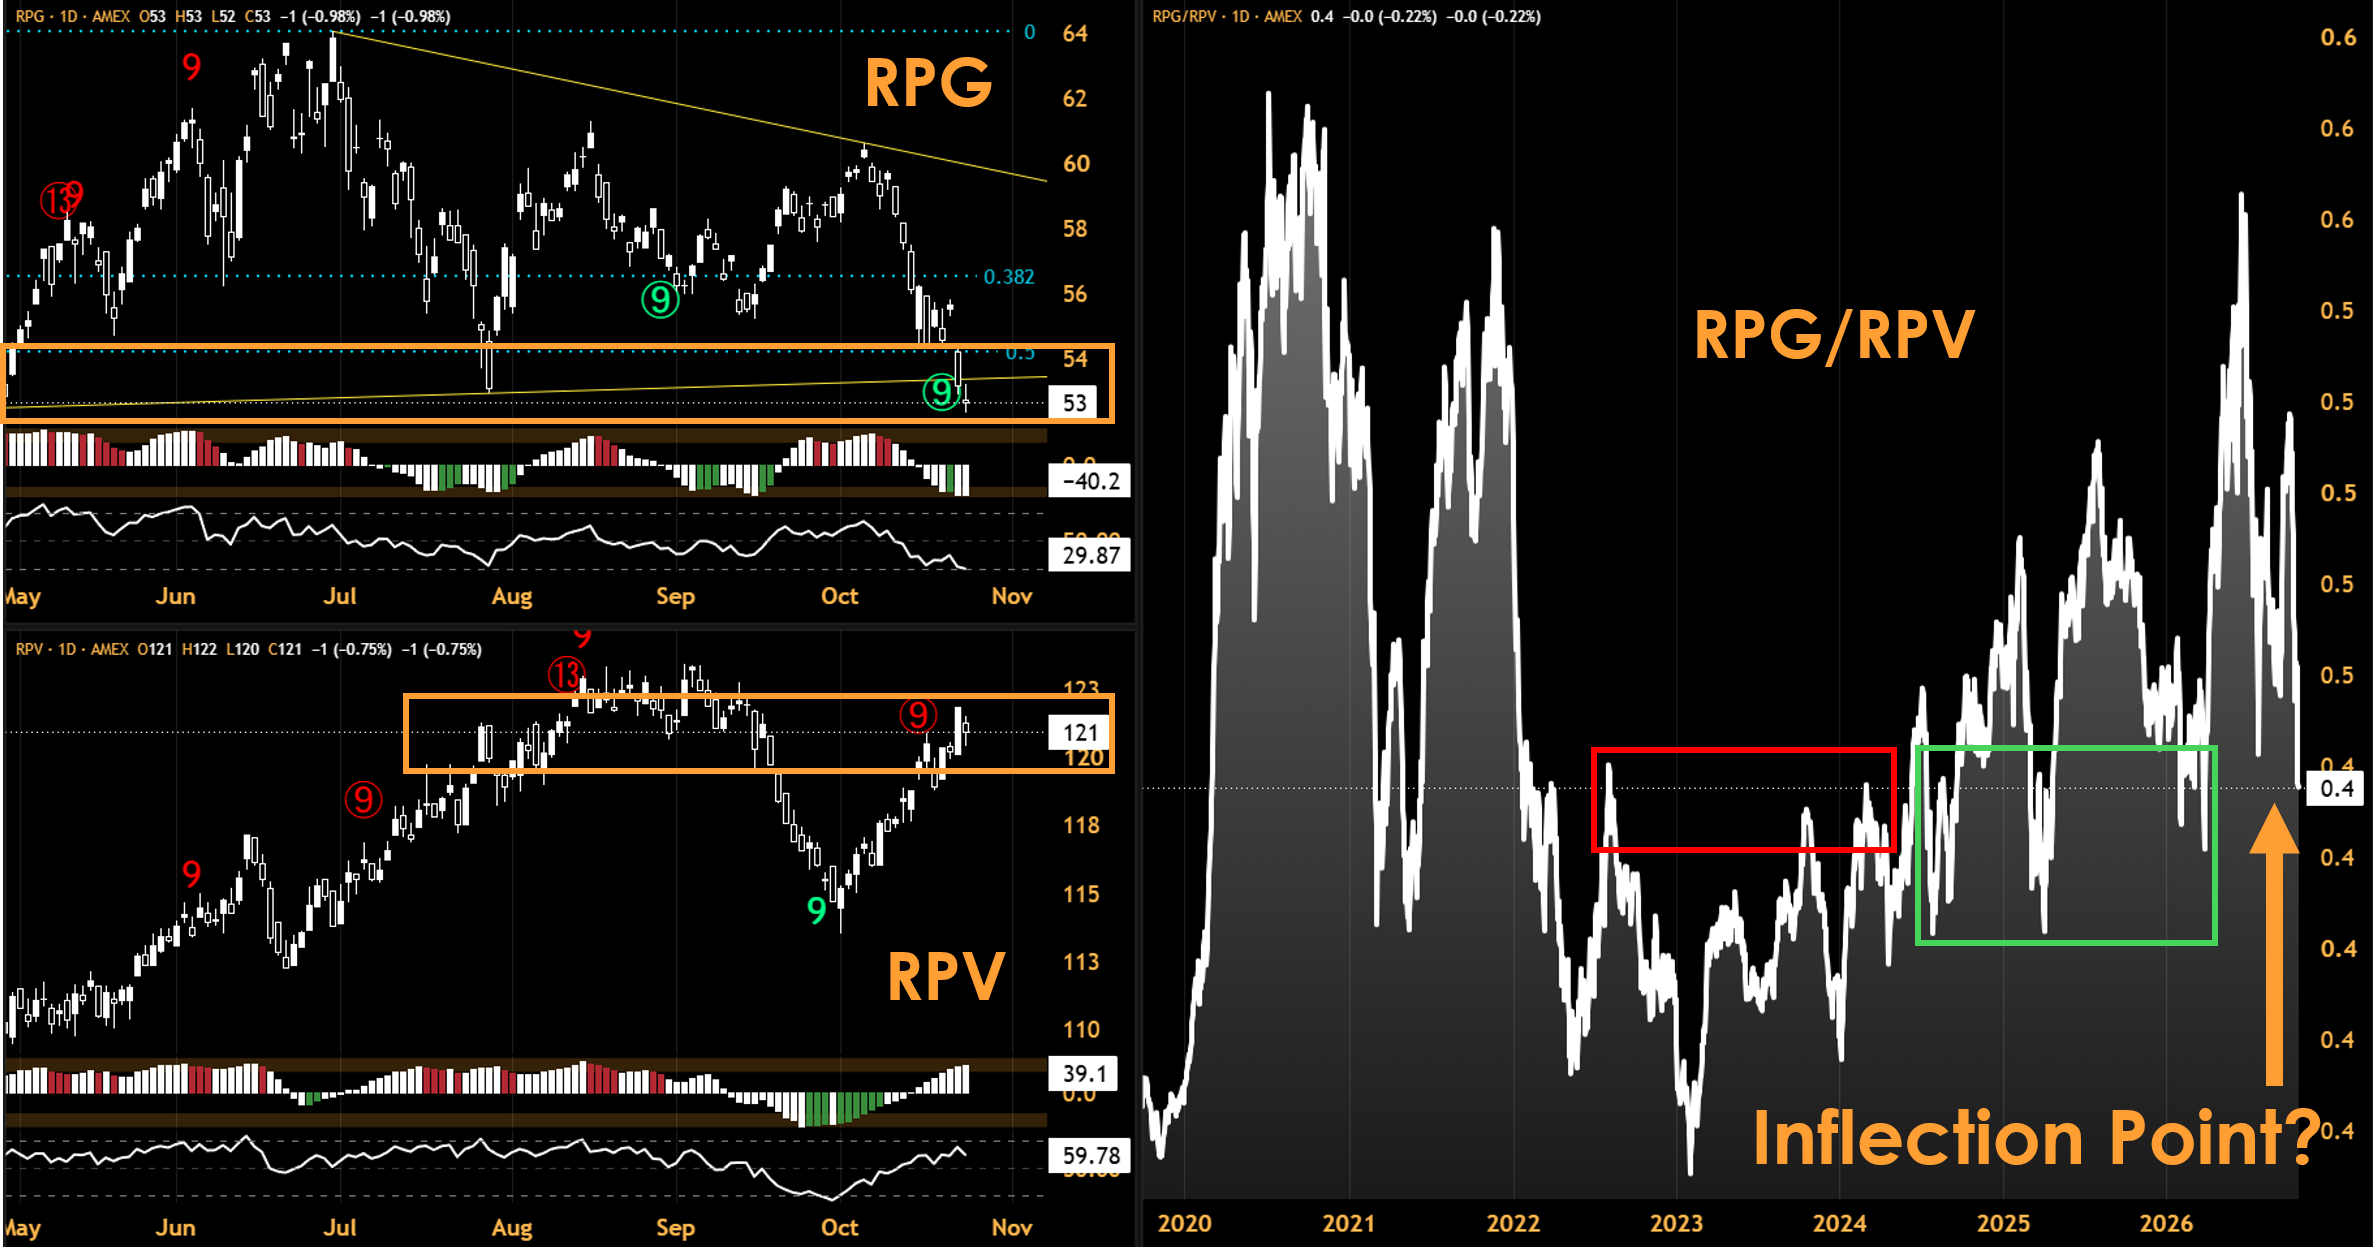
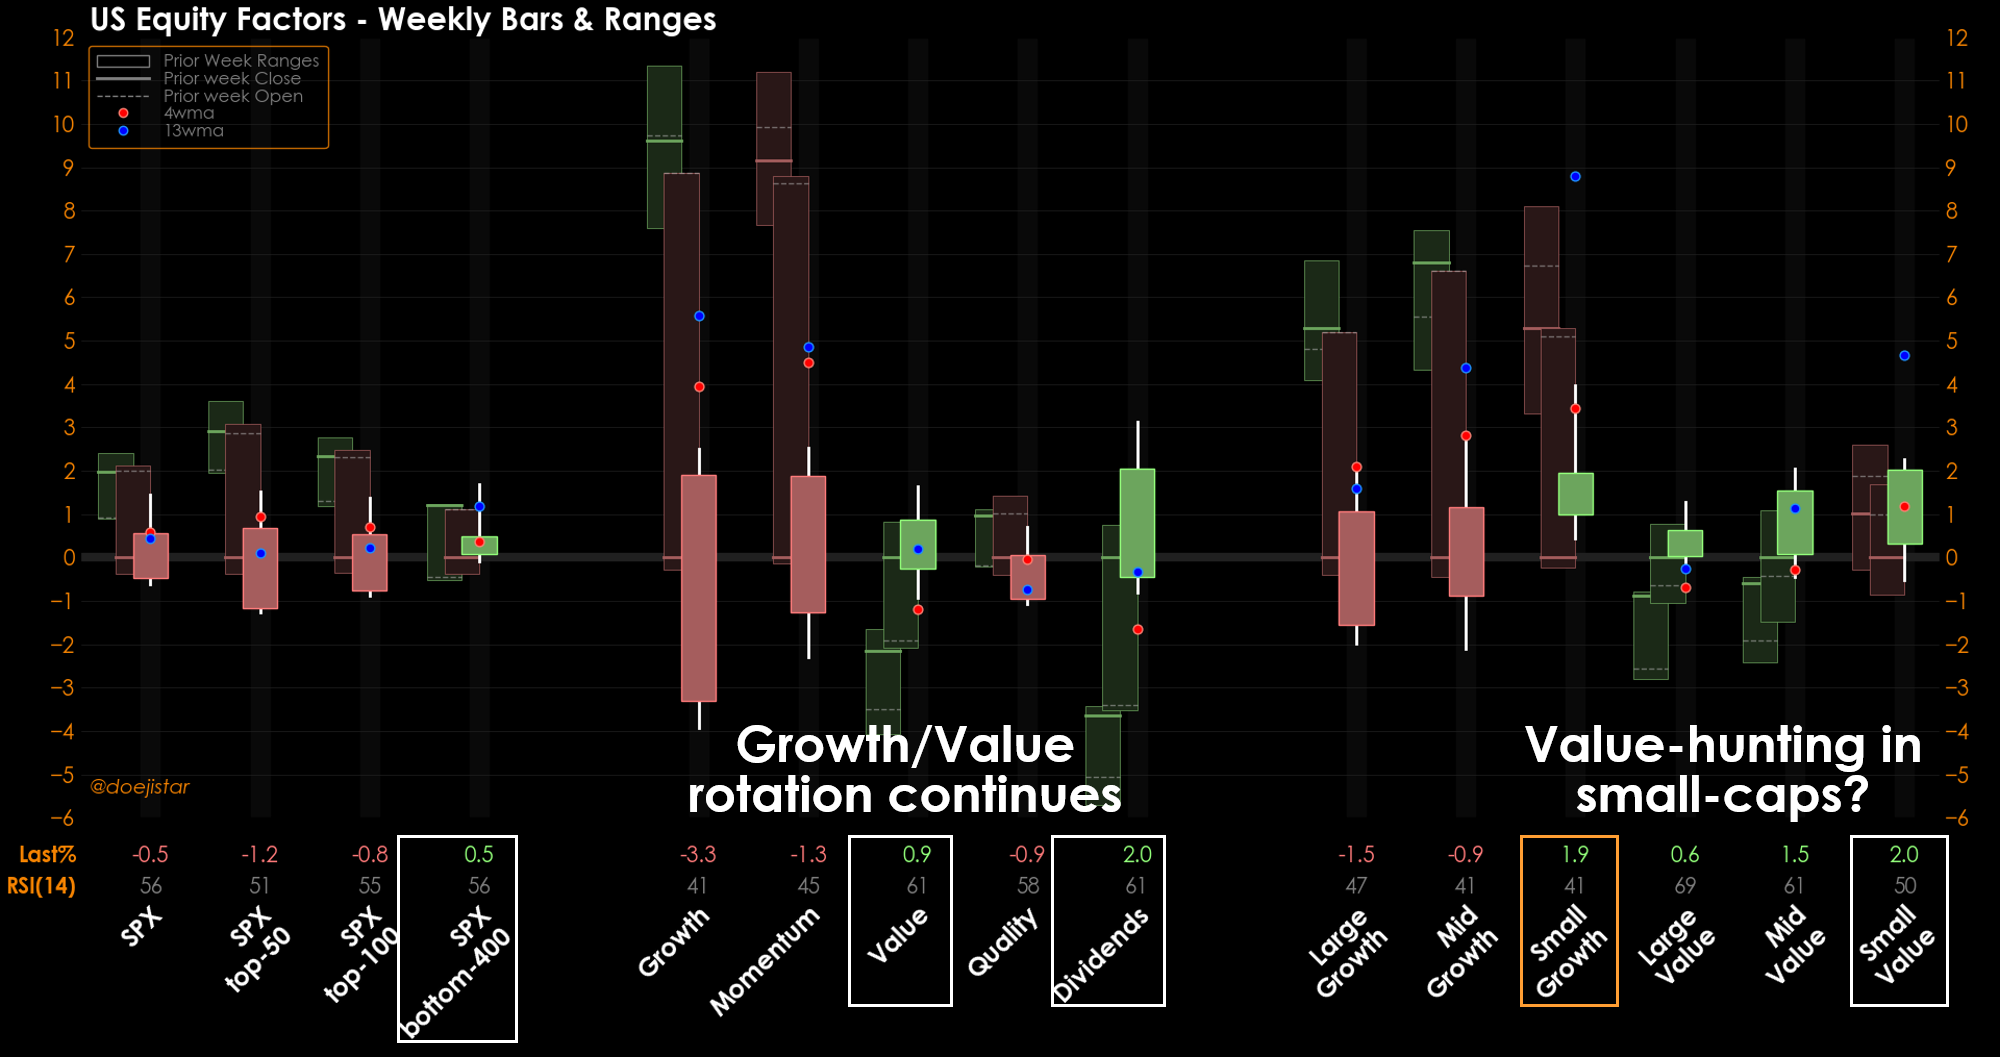
While the technical exhaustion signals did not hold up as a precise turning point last week, I still firmly believe we are in the area where the 'factor' pivot can occur. Interestingly, small-cap growth put in a positive weekly gain last week.
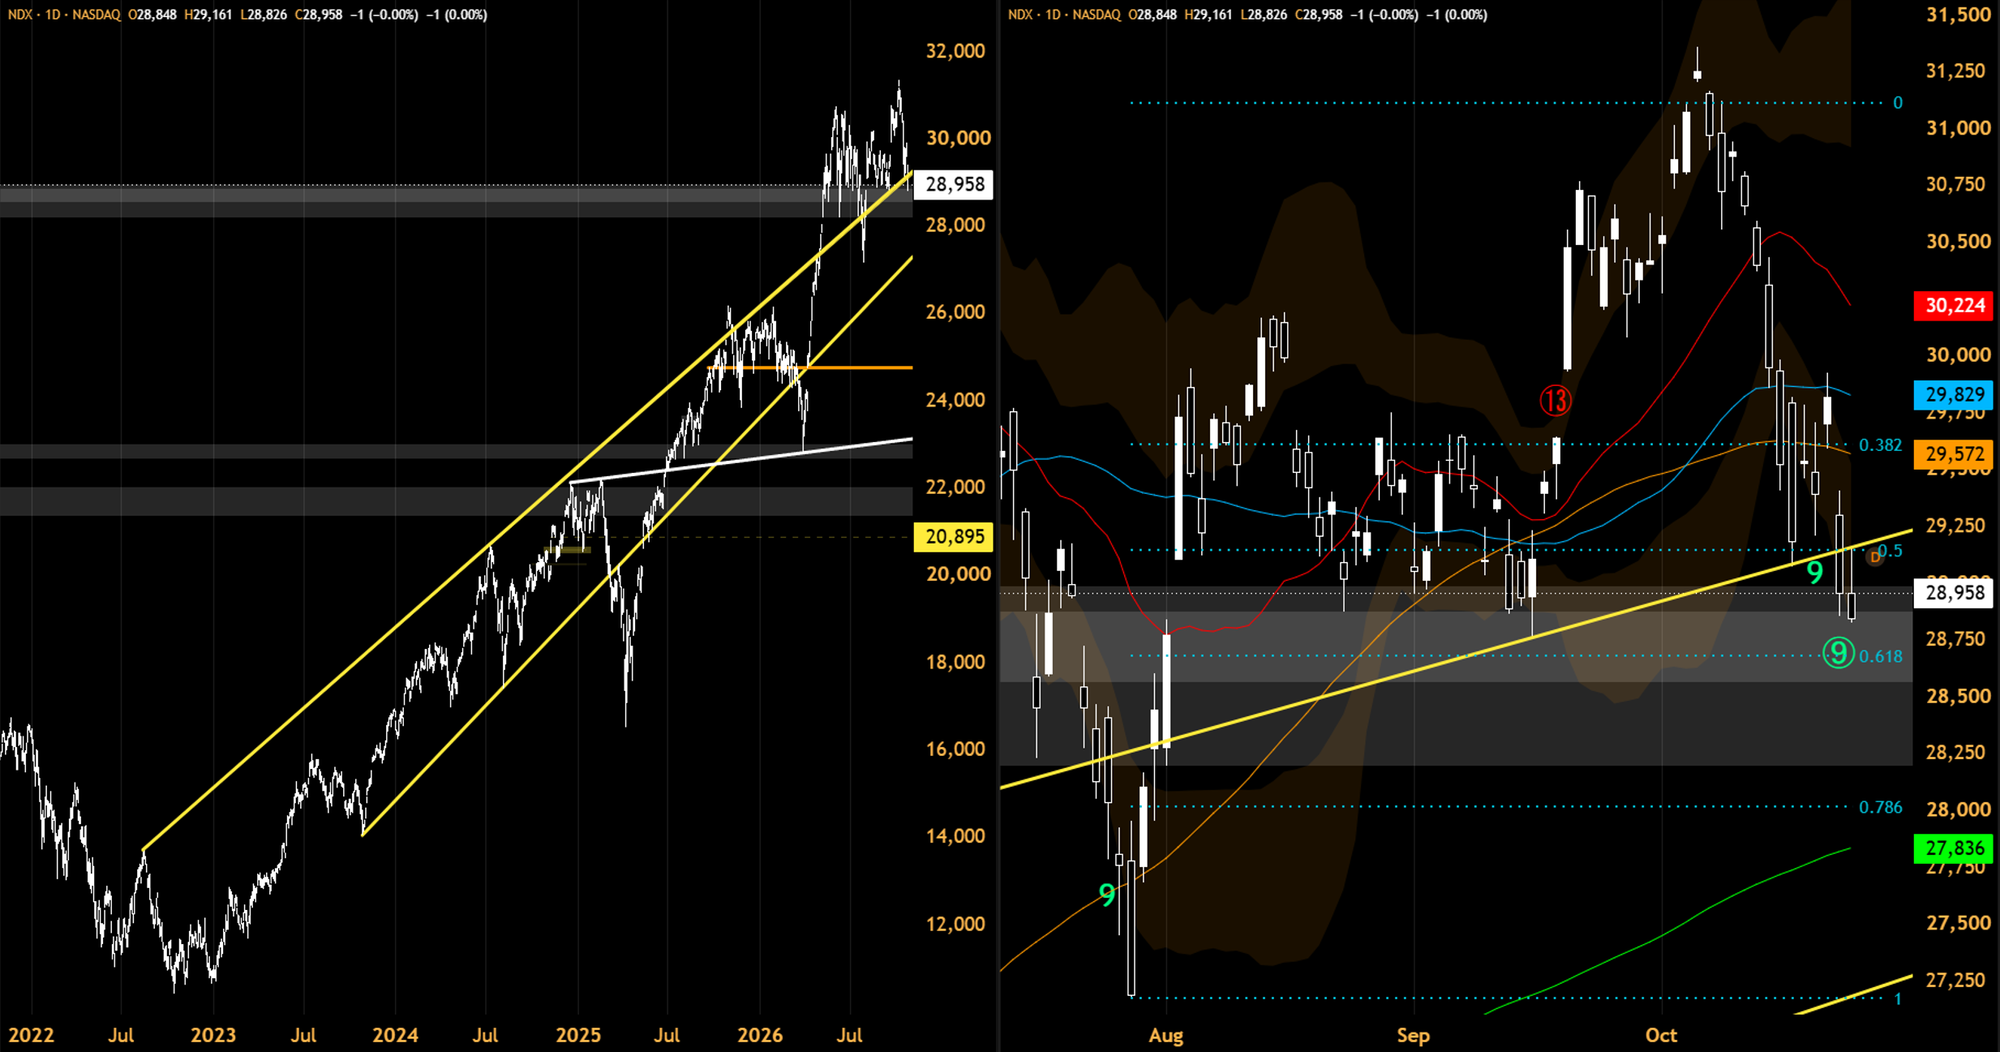
But we do have to contend with very elevated geopoltical risks with potentially another US-Iran escalation along with election uncertainties from various parts of the world. NDX put in another down leg after brief consolidation to keep momentum bearish, but there is some decent support underneath.
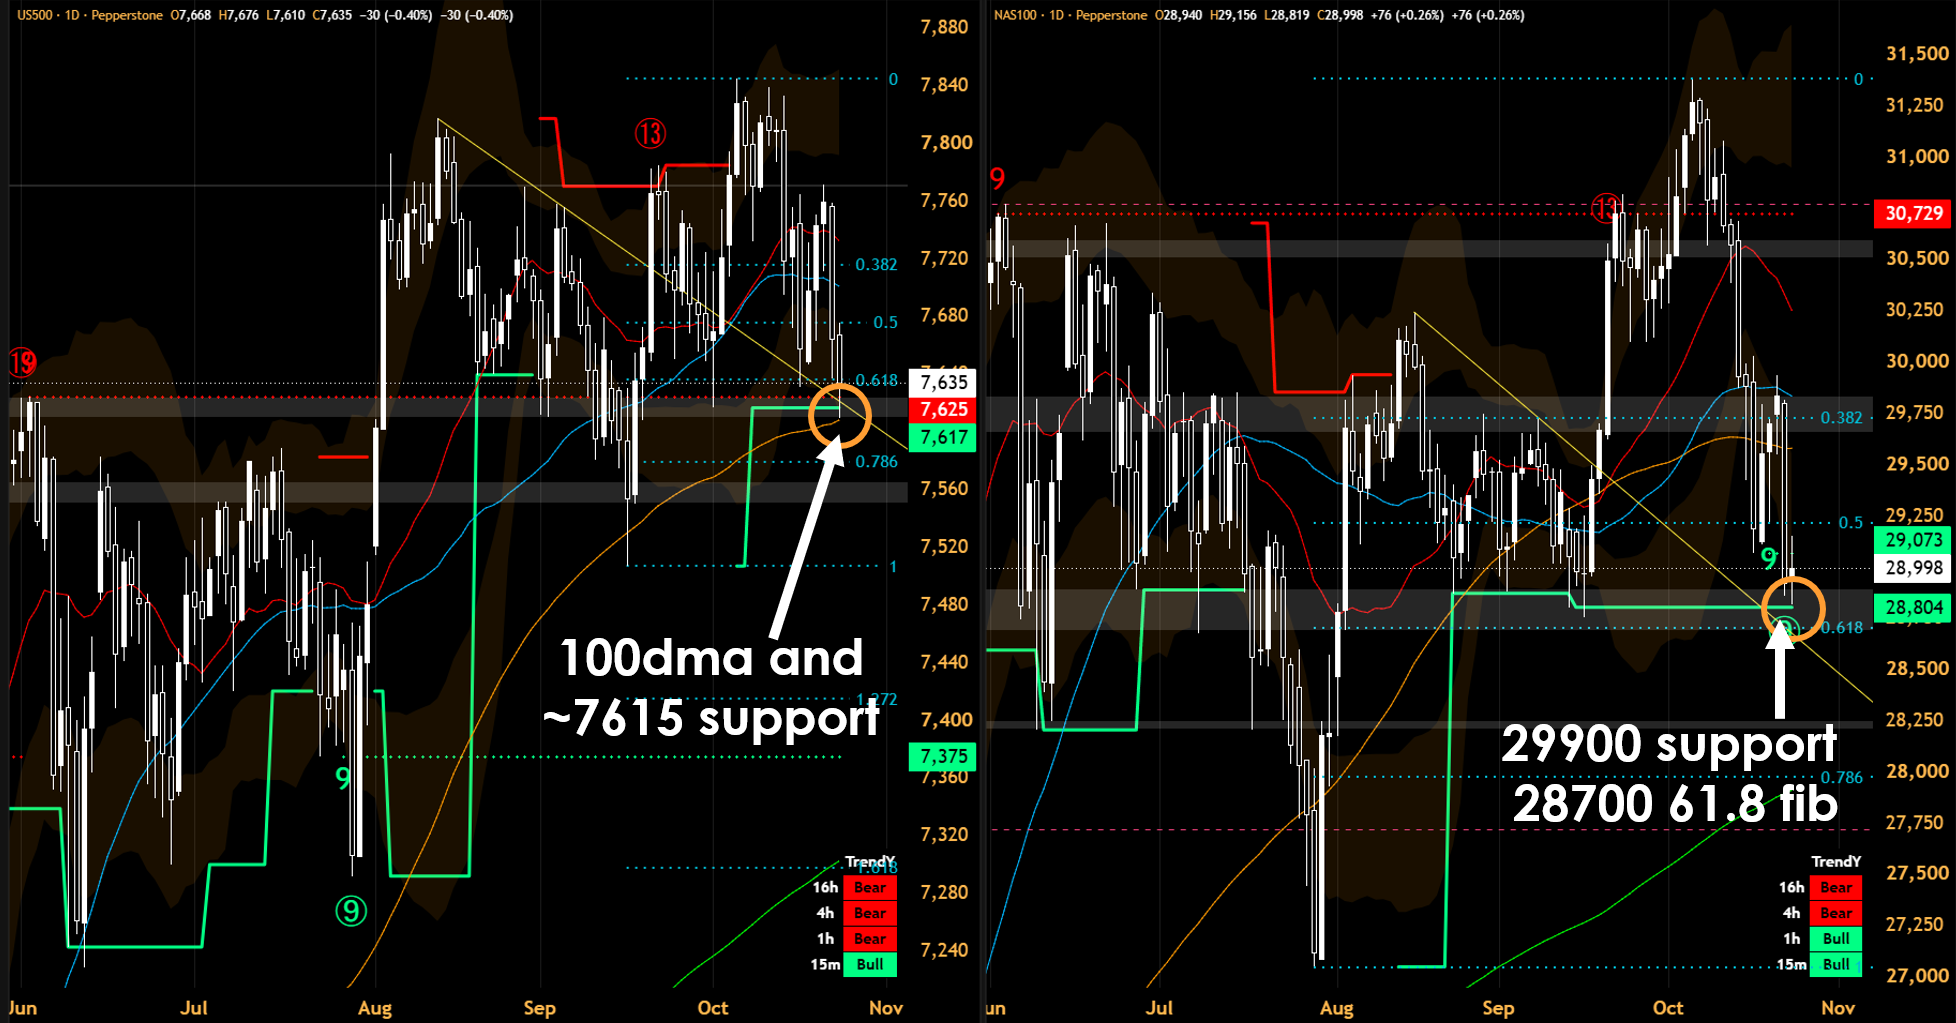
US500 and NAS100 held support areas on Friday but will need to show some upside confirmation. Interestingly, TrendY suggests the uptrend on the Daily timeframe is still intact unless it closes below the 7617 and 28804 levels.
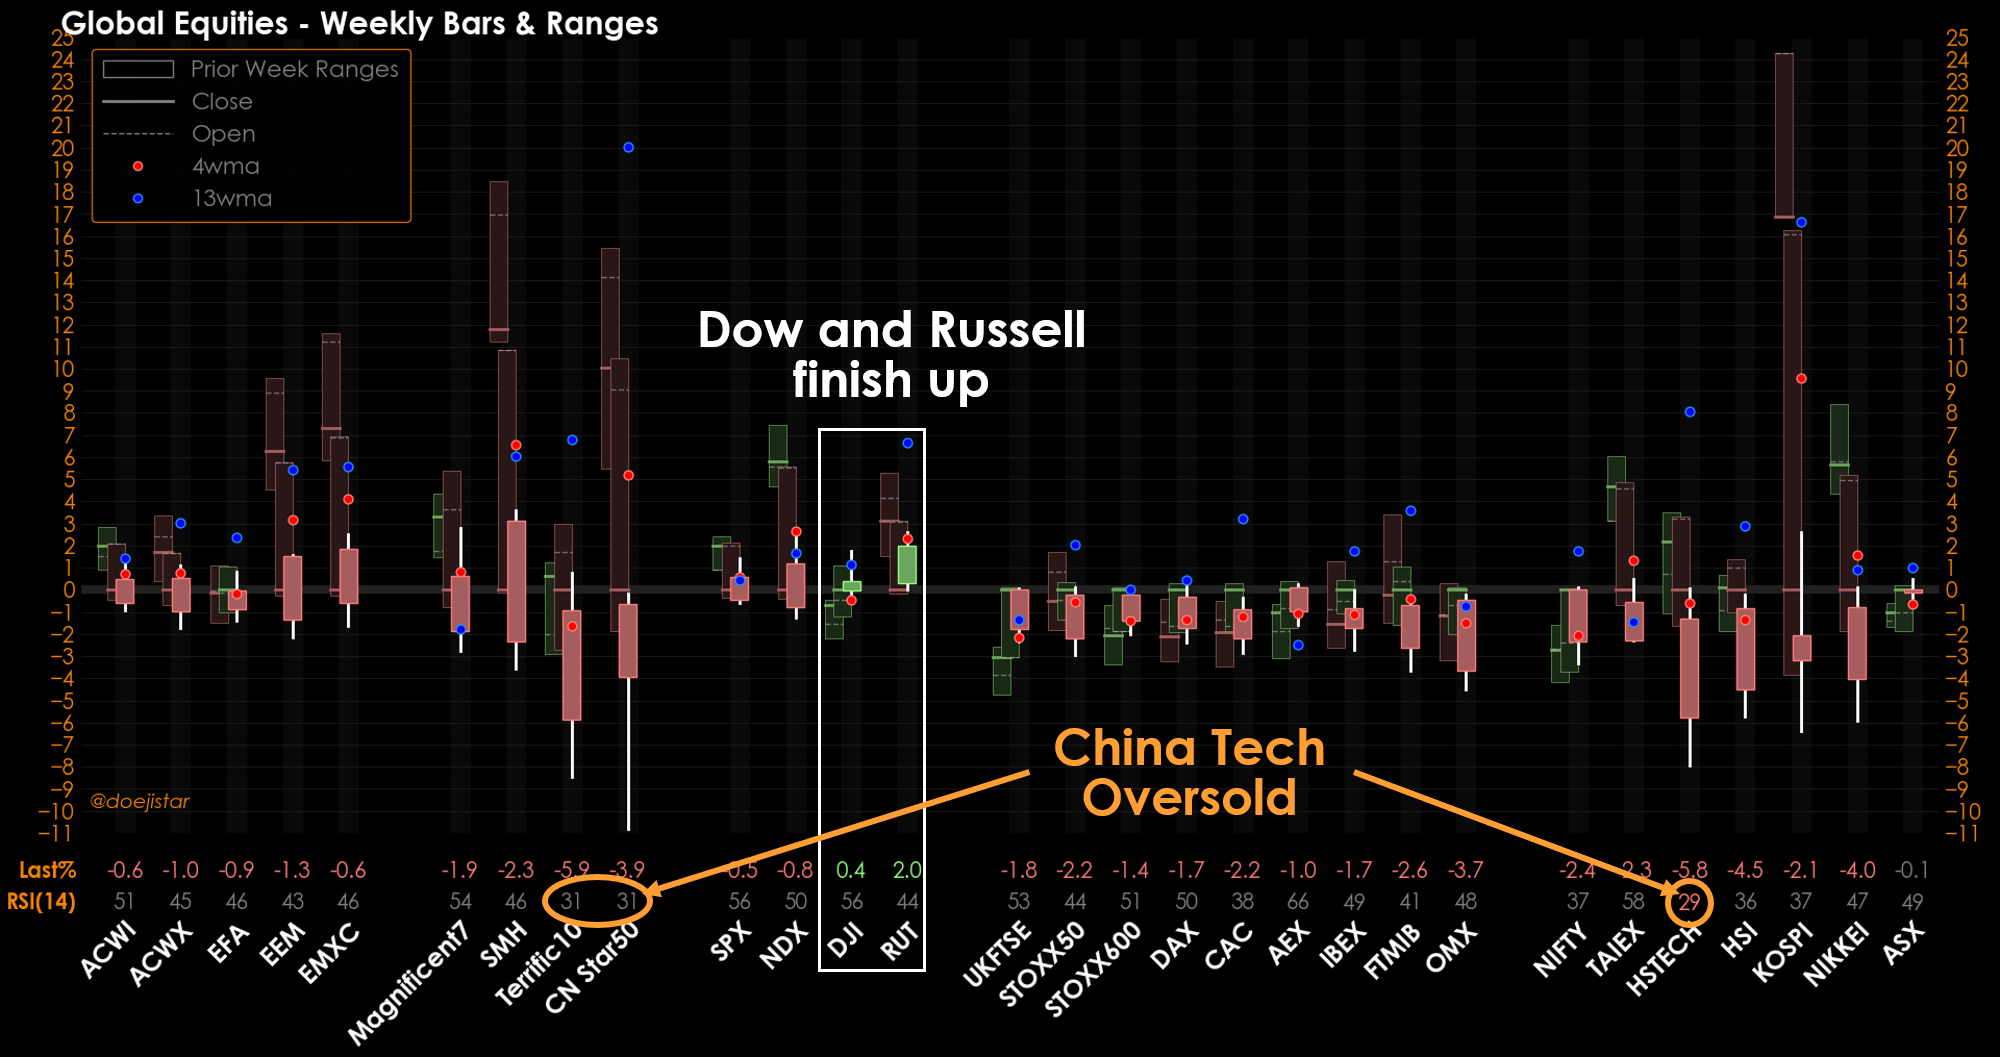
A few noticeable developments across global equity markets:
- Global indices being around the 40~50 Weekly RSI area tends to be associated with natural 5%ish pullbacks;
- DJIA and RUT closed higher last week; and
- China deeply oversold, KOSPI not far behind with 37 weekly RSI.
We're yet to see clear inflection signals but we're around key technical levels, RSIs neutralised to midpoint areas, but support needs to translate into upside confirmation. A break below support however would suggest the adjustment has further to run, and elevated geopolitical risk still keeps conviction levels relatively low, conditional, and timing uncertain. Perhaps midterms and the next escalation with Iran … mark the next bottom.
Inverted VIX